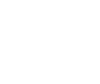


Australia’s Treasurer Jim Chalmers attends a press conference in Canberra, Australia on July 8, 2025. David Gray/AFP via Getty Images
The Australian Chamber of Commerce and Industry (ACCI) has told the federal government its proposed tax concession for innovative start-ups remains too complex, even after some of its toughest rules were softened.
It is designed to mitigate the effect of a much bigger change: from July 1, 2027, the government will scrap the standard CGT discount for all asset sales, replacing it with inflation indexation and a minimum 30 percent tax rate—effectively costing Australians more.
ACCI’s submission welcomed three changes Treasury made after industry raised concerns including:
Related Stories
-
Extending the eligibility period for start-up to qualify for a tax concession from 10 years to 15 years;
-
Cutting the holding period for how long an investor must keep their shares before selling them to claim the discount, from five to three years; and
-
Scrapping a proposed $10 million cap, which would limit how much of a discount an investor could claim.
But the Chamber said this redesign does not address its main concern, which is that the concessions were effectively a “narrow carve-out” to limit the “damage” of the overhaul to a small group of businesses.
ACCI Chief Executive Andrew McKellar says the rules are so complex that many genuinely innovative businesses will miss out, and those that qualify will spend more time on paperwork than on growing.
To qualify, a start-up must prove it meets a strict, multi-part definition of “innovative,” register with a government department, and keep filing annual reports for as long as its investors want the tax break.
The real problem, ACCI says, is who pays when something goes wrong: not the start-up, but the investor.
“An investor could meet every requirement applying to them, hold the interest for the required period and still lose access to the concession because the company lodged an annual report late or failed to meet the Industry Secretary’s reporting requirements,” the submission said.
That risk is real.
The rules also shut out foreign investors and require most of a start-up’s staff and assets to stay in Australia, cutting off foreign-sourced money that many start-ups need to grow. And the concession only rewards tech-style start-ups.
ACCI says mining, farming, manufacturing and professional services innovate too, but would not qualify.
ACCI wants simpler rules, investors protected from a company’s mistakes, and an independent review of the scheme within two years.